Setting up a UAE Free Zone Company vs. Individual Ownership: What Pakistani Investors Should Know
Executive Introduction
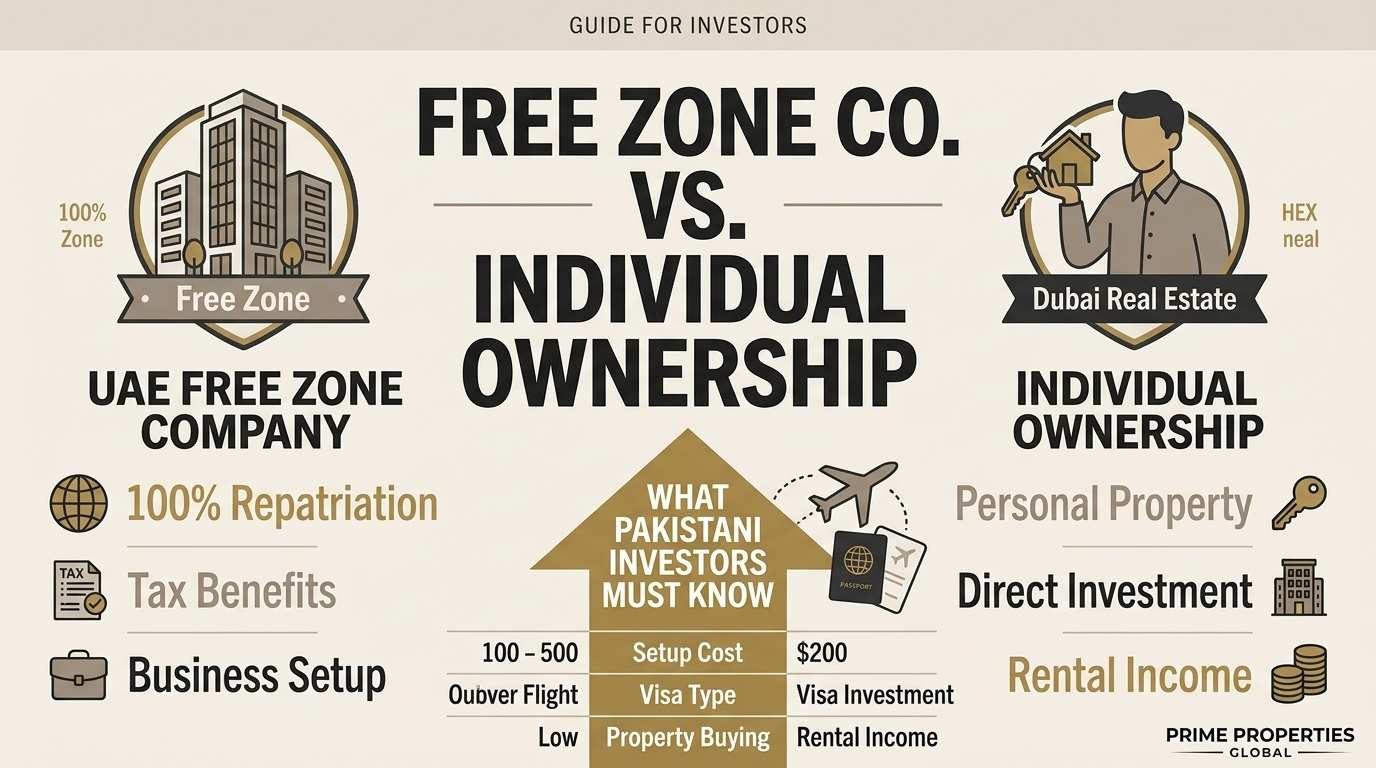
As Pakistani investors expand their international real estate portfolios in the UAE, a strategic decision arises: should properties be purchased in an individual capacity or structured through a UAE Free Zone company (such as Meydan Free Zone, IFZA, or JAFZA)? Both methods offer unique advantages regarding asset protection, taxation, estate planning, and visa eligibility.
1. Ownership Mechanics and Legal Structures
- Individual Ownership: Individual buyers register title deeds directly under their personal passport name with the Dubai Land Department (DLD). This process is straightforward, requires minimal setup paperwork, and carries standard DLD registration fees (4%).
- Corporate/Free Zone Ownership: Properties are held under the legal title of a UAE Free Zone entity or Holding Company. The individual owns 100% of the Free Zone company, which in turn owns the real estate assets. Specific Free Zones are approved by DLD for property registration.
2. Comparative Overview: Individual vs. Corporate Holding
| Feature | Individual Ownership | UAE Free Zone Corporate Setup |
|---|---|---|
| Setup & Annual Fees | Zero initial company setup costs | Annual license renewal fees (~AED 12k–20k) |
| Estate Planning & Inheritance | Subject to UAE court probate / DIFC Will | Seamless transfer of company shares |
| Asset Protection | Personal liabilities attach to asset | Corporate liability shield |
| Golden Visa Eligibility | Directly eligible (if AED 2M threshold met) | Eligible through company ownership/manager role |
| Multi-Property Aggregation | Individual title deed for each unit | Consolidated portfolio under one entity |
| Banking Setup | Personal UAE Bank Account | Corporate UAE Bank Account |
3. Estate Planning and Succession Continuity
- Inheritance & Probate Rules: Individual property owners in the UAE without a registered DIFC Will are subject to UAE local court inheritance procedures upon death, which can temporarily freeze personal property assets during probate.
- Corporate Share Transfers: Holding real estate within a Free Zone company allows smooth succession. Family members can be added as company shareholders, enabling seamless equity transfer without re-registering individual property title deeds at the DLD.
4. Tax Implications and FBR Reporting
- Corporate Tax Rules in UAE: The UAE introduced a 9% Corporate Tax on business net profits exceeding AED 375,000. However, passive real estate income earned by entities or individuals is subject to specific exemption conditions that investors must structure correctly with tax advisors.
- FBR Declarations for Pakistan Taxpayers: Whether held individually or via a Free Zone entity, foreign real estate holdings and offshore company shares must be accurately disclosed in annual FBR Wealth Statements to remain fully compliant with Pakistani tax legislation.
Frequently Asked Questions
Q: Which UAE Free Zones are allowed to hold property in Dubai?
Answer: DLD-approved Free Zones include JAFZA, Meydan Free Zone, IFZA, and Dubai South, among others.
Q: Can a Free Zone company qualify for the UAE Golden Visa?
Answer: Yes, if the company holds qualifying real estate assets valued at AED 2 Million or above without encumbrances, or via executive director roles within the entity.
Q: Is corporate ownership more expensive than personal title holding?
Answer: Yes, corporate ownership incurs initial company formation costs and ongoing annual trade license renewal fees.
Rental Returns Comparison: DHA Lahore Phase 6/8/9 vs. Dubai Marina & JVC
Executive Introduction
When evaluating real estate investments, cash flow stability and rental yields are crucial indicators of asset health. For Pakistani investors, the debate between staying domestic in established sectors like DHA Lahore (Phases 6, 8, and 9) versus diversifying into Dubai’s high-demand hubs like Dubai Marina and Jumeirah Village Circle (JVC) comes down to yield percentages, currency stability, and capital appreciation potential.
1. Rental Yield Metrics: DHA Lahore vs. Dubai Hubs
- DHA Lahore (Phases 6, 8, 9): Residential properties in DHA Phase 6 and Phase 8 generate gross rental yields between 3.5% and 4.8%. Phase 9 Town, being newer with active development, sees slightly varied yields depending on plot delivery and occupancy rates. While capital appreciation has historically been high in PKR terms, gross yields are moderated by local market rental caps and currency depreciation.
- Dubai Marina & JVC: Dubai offers significantly higher cash-on-cash yields. JVC yields average 7.2% to 8.5% gross on residential apartments due to high tenant demand from young professionals. Dubai Marina commands 6.0% to 7.0% gross yield, backed by premium waterfront positioning and short-term holiday home rental options.
2. Comparative Financial Analysis
| Metric | DHA Lahore Phase 6 & 8 | Dubai Marina | Dubai JVC |
|---|---|---|---|
| Average Gross Yield | 3.8% – 4.8% | 6.0% – 7.0% | 7.5% – 8.8% |
| Net Rental Yield (Est.) | 2.8% – 3.8% | 4.8% – 5.8% | 6.0% – 7.2% |
| Currency Exposure | PKR (High inflation risk) | AED (Pegged to USD) | AED (Pegged to USD) |
| Maintenance Fees | Low (Direct Landlord) | Service Charges (Medium) | Service Charges (Moderate) |
| Property Tax Impact | FBR advance & rental income tax | 0% Property Tax / Income Tax | 0% Property Tax / Income Tax |
3. Currency Hedging and Inflation Protection
- PKR Yield Erosion: A 4.5% yield in DHA Lahore can be substantially eroded in real terms if the Pakistani Rupee devalues against major international currencies. Investors earning rent in PKR face diminished global purchasing power.
- AED USD Peg Advantage: Dubai properties generate rental returns in United Arab Emirates Dirham (AED), which is pegged to the US Dollar. This provides built-in protection against currency volatility, making Dubai cash flow ideal for investors funding international expenses, education, or foreign business trips.
4. Property Management and Maintenance Overhead
- Self-Management in Lahore: In DHA Lahore, managing tenants directly or via local brokers is straightforward and carries minimal maintenance fee structures outside society charges. However, tenant turnover and rent collection delays can occasionally occur.
- Dubai Service Charges & HOA: Dubai properties are subject to official RERA-regulated service charges (calculated per square foot). While these cover building maintenance, pool, and gym facilities, they reduce gross yield down to net yield. Professional property management companies in Dubai typically charge 5% to 8% of annual rent for end-to-end management.
Frequently Asked Questions
Q: Which location gives higher net rental yield: DHA Lahore or Dubai JVC?
Answer: Dubai JVC offers higher net rental yields (6.0% - 7.2%) compared to DHA Lahore (2.8% - 3.8%), even after accounting for Dubai property service fees.
Q: Are rental income taxes applied in Dubai for Pakistani residents?
Answer: Dubai charges 0% personal income tax and 0% property tax on rental income. However, Pakistani tax residents must declare foreign assets and foreign income in their FBR annual tax filings.
Q: Is DHA Lahore better for capital appreciation than Dubai?
Answer: Historically, DHA Lahore offers strong long-term capital appreciation in local PKR terms, whereas Dubai offers strong cash flow stability in USD/AED along with cyclic capital growth.
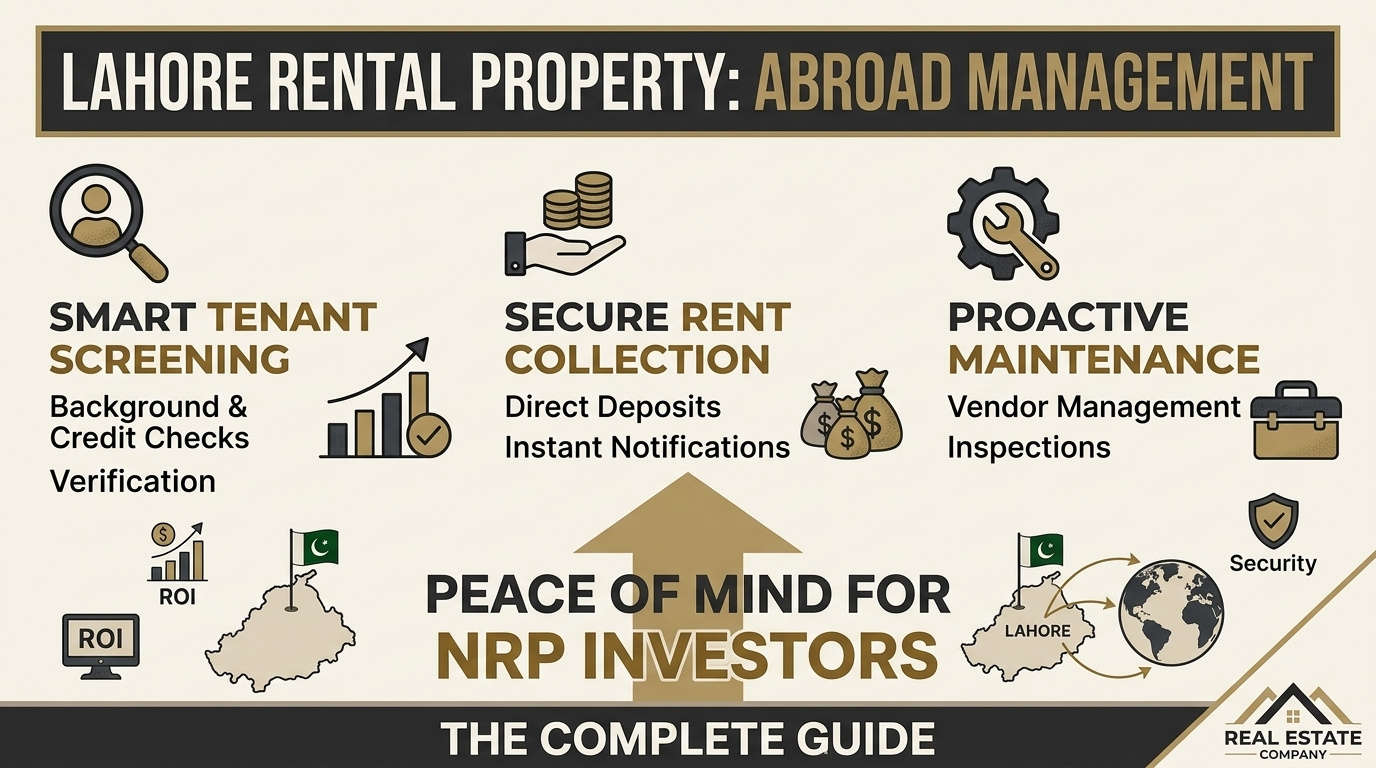
Managing Rental Property in Lahore from Abroad: Tenant Screening, Rent Collection, and Maintenance
Executive Introduction
Owning income-generating real estate in prime Lahore sectors like DHA Phase 5, Phase 6, Gulberg, or Bahria Town provides steady rental revenue. However, for landlords residing in the UAE, UK, or USA, managing tenant relationships, property repairs, and legal contracts remotely can be challenging without structured operational systems.
1. Standardized Tenant Screening Process
- Verification Requirements: Never rent out a residential or commercial property in Lahore without thorough background checks. Require CNIC/NICOP copies, proof of employment or business registration, bank statements, and references from previous landlords.
- Police Verification Mandatory Requirement: Under Punjab Information of Temporary Residents Act, landlords must register tenant details with the local Lahore Police Station (via the Punjab Police Hotel Eye / Tenant Registration app) within 15 days of occupancy to ensure legal compliance.
2. Modern Property Management Framework
| Management Pillar | Traditional Local Approach | Recommended Remote Digital System |
|---|---|---|
| Tenancy Agreement | Paper stamp paper signed in person | E-Stamp Paper + Digital signature / POA |
| Rent Collection | Cash / Local physical checks | Raast instant bank transfer / Automated RDA deposit |
| Property Inspections | Ad-hoc family visits | Bi-annual professional inspection report with photos |
| Maintenance Requests | Direct calls to landlord | Property management agency or dedicated local caretaker |
3. Drafting Watertight Tenancy Agreements in Lahore
- Key Contractual Clauses: Ensure the tenancy agreement is drawn on official Punjab E-Stamp paper. Explicitly state the 11-month contract duration (renewable), annual rent escalation clause (typically 10%), security deposit terms (usually 2 to 3 months), and utility bill payment obligations (LESCO, SNGPL, Water, Society Maintenance).
- Eviction and Renewal Protection: Include clear notice period terms (1 or 2 months) and penalties for late payment or unauthorized property modifications.
4. Hiring Professional Property Management Agencies vs. Family Delegation
- Pitfalls of Relying on Relatives: Delegating management to friends or relatives often leads to miscommunication, delayed inspections, or awkwardness when enforcing strict rent payment deadlines.
- Professional Agency Advantages: Specialized real estate agencies in Lahore charge a fee (typically 1 month's rent or 5%-8% monthly commission) to handle tenant sourcing, contract execution, emergency plumbing/electrical repairs, and rent collection professionally.
Frequently Asked Questions
Q: Is tenant police verification compulsory in Lahore?
Answer: Yes, registering tenant details with local Lahore Police is legally mandatory for safety and property security.
Q: How can overseas landlords legally execute tenancy contracts remotely?
Answer: Overseas landlords can execute contracts through Special Power of Attorney (POA) attested by the local Pakistan Embassy/Consulate or digitally via E-Stamp mechanisms.
Q: What is the typical security deposit in DHA Lahore?
Answer: The standard security deposit in DHA Lahore ranges between 2 to 3 months of gross monthly rent.
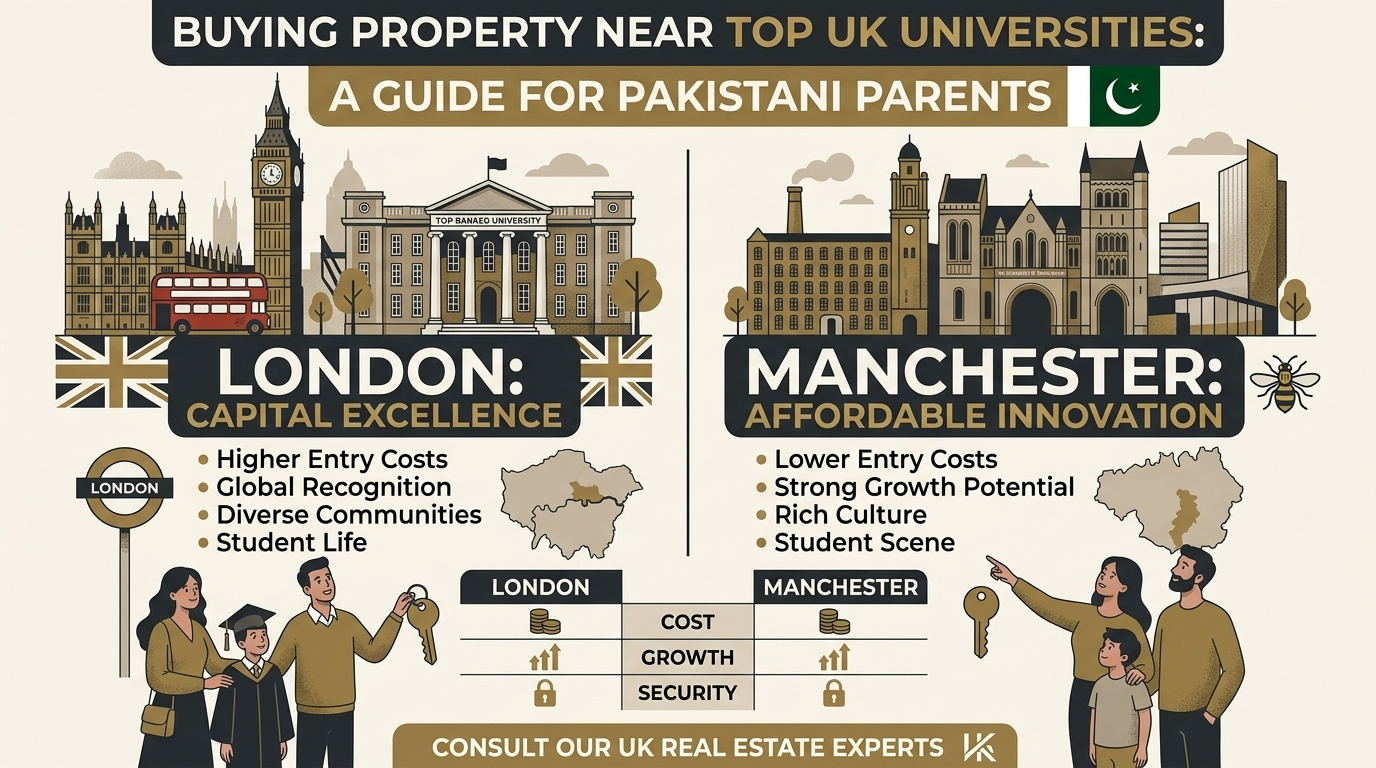
Buying Property near Top UK Universities: A Guide for Pakistani Parents Sending Children Abroad (London vs. Manchester)
Executive Introduction
Sending children to study at world-renowned UK institutions—such as Imperial College, LSE, UCL, King's College in London, or the University of Manchester—is a major milestone for Pakistani families. Rather than paying high non-refundable student housing rent, forward-thinking parents are increasingly purchasing residential properties near these universities to secure accommodation and build long-term pound sterling real estate equity.
1. Strategic Rationale: Rent vs. Equity Building
- Eliminating Rental Sunk Costs: Prime student rentals in central London can easily cost £2,000 to £3,500 per month. Purchasing a 2-bedroom apartment eliminates accommodation expenses and turns living expenses into property equity.
- Roommate Income Generation: By purchasing a multi-bedroom flat, student children can live in one room while renting out the second bedroom to a fellow university student, generating steady GBP rental cash flow to offset monthly utility and management fees.
2. Regional Comparison: London vs. Manchester
| Factor | London (Zone 1 - 3) | Greater Manchester |
|---|---|---|
| Top Universities | UCL, LSE, Imperial, King's, Queen Mary | University of Manchester, MMU |
| Average 2-Bed Price | £650,000 – £1,200,000+ | £230,000 – £380,000 |
| Average Gross Yield | 3.2% – 4.5% | 6.0% – 7.5% |
| Stamp Duty (SDLT) | Higher tier (Includes 2% Non-Resident Surcharge) | Lower baseline purchase tax |
| Tenant Capital Growth | Steady long-term capital preservation | High growth potential (Northern Powerhouse) |
3. UK Tax and Legal Rules for Non-Resident Pakistani Buyers
- Stamp Duty Land Tax (SDLT): Non-resident buyers purchasing UK residential property are subject to standard SDLT rates plus a 2% Non-UK Resident Surcharge and a 3% Higher Rates for Additional Dwellings (HRAD) surcharge if owning other properties worldwide.
- UK Non-Resident Landlord Scheme (NRLS): If renting out part or all of the property, Pakistani owners must register under the NRLS to receive gross rent without automatic 20% withholding tax by letting agents, allowing tax reporting through annual UK self-assessment filings.
4. Mortgage Options for Pakistani Residents
- UK Expat & International Mortgages: Pakistani residents can secure UK buy-to-let or expat mortgages through UK-regulated international banks or Islamic financing institutions (e.g., Gatehouse Bank, Al Rayan Bank). Maximum Loan-to-Value (LTV) typically ranges between 60% and 75%.
- Documentary Requirements: Lenders require proof of foreign income, bank statements, audited business accounts (for business owners), source of wealth declarations, and proof of student enrollment.
Frequently Asked Questions
Q: Can a Pakistani student in the UK hold property title deeds?
Answer: Yes, individuals aged 18 and over can legally hold property title deeds in the UK regardless of nationality or visa status.
Q: What is the average yield difference between London and Manchester student flats?
Answer: Manchester generally yields significantly higher returns (6.0% - 7.5%) compared to Central London (3.2% - 4.5%).
Q: Is Islamic Sharia-compliant financing available for overseas buyers in the UK?
Answer: Yes, UK-based Islamic lenders offer Sharia-compliant Diminishing Musharaka property financing to overseas non-resident buyers.
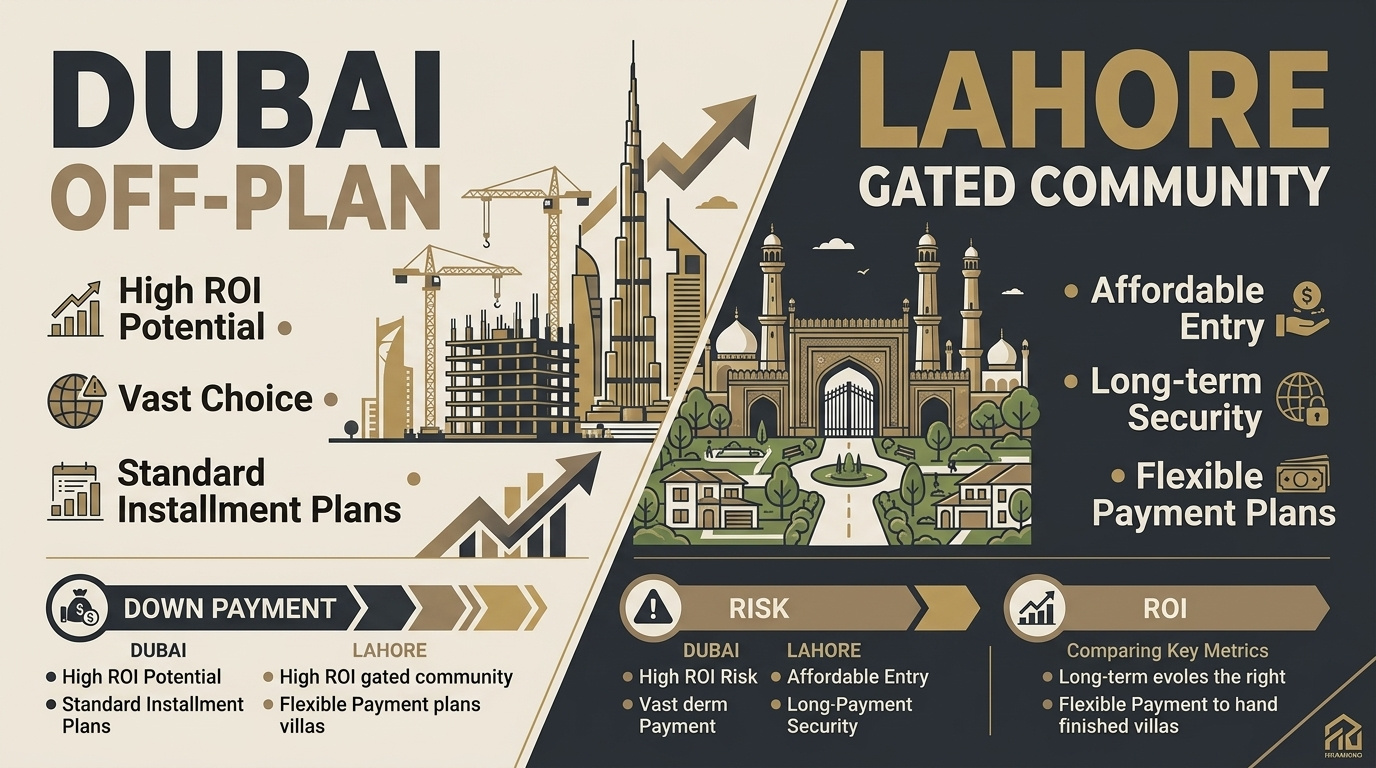
Dubai Off-Plan vs. Lahore Gated Community Installment Plans: Down Payment, Risk, and ROI Breakdown
Executive Introduction
Flexible installment plans are the preferred entry point for real estate investors looking to build assets without paying 100% upfront capital. Both Dubai off-plan projects and Lahore gated community developments (such as DHA Phase 9 Prism, Bahria Town, or suburban master-planned communities) offer multi-year payment structures, but they operate under vastly different regulatory frameworks, risk profiles, and return metrics.
1. Entry Costs and Down Payment Structures
- Dubai Off-Plan Requirements: Typical Dubai off-plan projects require a 10% to 20% down payment, plus a 4% Dubai Land Department (DLD) transfer fee and admin fees. Payment plans are linked either to construction milestones (e.g., 60/40 or 50/50) or post-handover terms spanning 1 to 3 years after project completion.
- Lahore Gated Communities: Lahore installment plans often feature lower initial entry thresholds—frequently 10% to 15% booking down payment, with quarterly or monthly installments spanning 3 to 5 years. Balloting and development charges are billed separately as construction progresses.
2. Escrow Protection and Regulatory Framework
| Feature | Dubai Off-Plan Projects | Lahore Gated Communities |
|---|---|---|
| Regulatory Authority | RERA / Dubai Land Department (DLD) | LDA / RUDA / Housing Authorities |
| Buyer Funds Protection | Mandatory RERA Escrow Account | Developer Direct Account |
| Construction Audit | Government audited milestones | Internal developer timeline |
| Delay Penalty Provisions | Contractual refund / penalty clauses | Variable society extension terms |
| Resale Flexibility | Permitted after 30%-40% payment | Transfer files permitted via society office |
3. Completion Risk and Delivery Timelines
- RERA Escrow Security in Dubai: Dubai law strictly requires developers to deposit buyer funds into project-specific escrow accounts. Funds are released to developers only as verified construction milestones are achieved. This drastically minimizes project abandonment risk.
- Development Timelines in Lahore: In Lahore, while reputed developers (like DHA or major private builders) deliver reliably, suburban gated schemes may experience land acquisition delays, infrastructure installation lags, or delayed NOC approvals from local authorities like LDA. Investors must perform rigorous due diligence on land title status.
4. Capital Appreciation and Exit Strategies (ROI)
- Off-Plan Flipping in Dubai: Investors in Dubai off-plan properties can legally resell (flip) their units before handover once a specified percentage (usually 30% to 40%) of the purchase price is paid, capturing equity gains in a rising market.
- File Trading in Lahore: In Lahore, buying affidavit or plot files on installments allows investors to gain from file rate appreciation as balloting approaches. However, liquidity can fluctuate based on local market sentiment, interest rates, and macro-economic factors.
Frequently Asked Questions
Q: Can non-resident Pakistanis buy Dubai off-plan properties remotely?
Answer: Yes, Dubai off-plan purchases can be completed 100% remotely using digital contracts, official developer payment portals, and bank transfers.
Q: What happens if a developer delays project completion in Dubai vs. Lahore?
Answer: In Dubai, RERA monitors progress and enforces contractual delay penalties or project reassignment. In Lahore, buyers rely on society terms, consumer courts, or developer reputation management.
Q: Which option requires less initial capital?
Answer: Lahore gated community installment plans generally require lower initial PKR outlays compared to Dubai properties when converted to USD/AED.
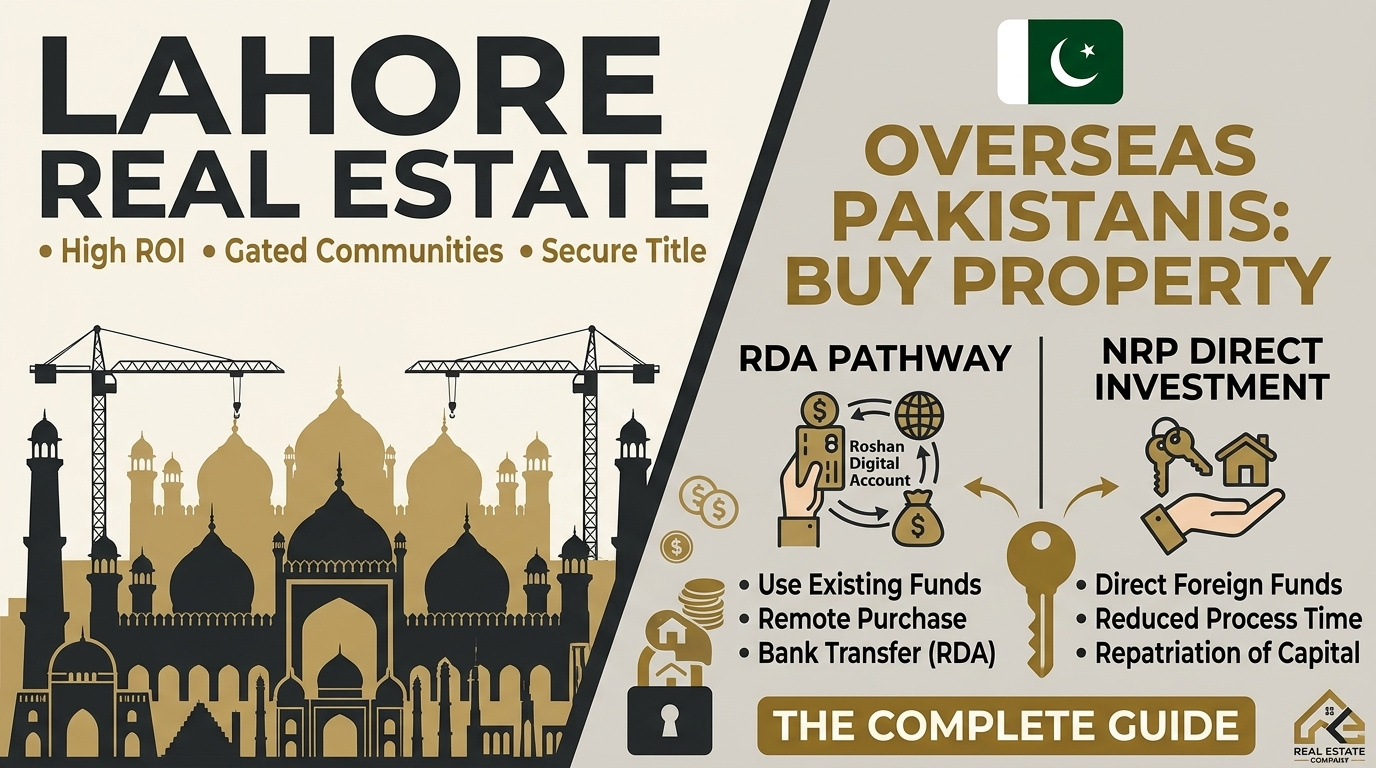
How Overseas Pakistanis Can Buy Property in Lahore Using RDA (Roshan Digital Account) & NRP Direct Investment
Executive Introduction
The State Bank of Pakistan (SBP) created the Roshan Digital Account (RDA) framework to streamline cross-border financial transactions for Non-Resident Pakistanis (NRPs). Through 'Roshan Equity' and 'Roshan Apni Real Estate', overseas Pakistanis can now purchase residential and commercial property in Lahore transparently, enjoy full repatriation of funds, and avoid legal bottlenecks.
1. What is the RDA Real Estate Route?
- State Bank Integration: Roshan Apni Real Estate connects RDA banking portals directly with SBP-approved real estate projects and reputed developments in Lahore. It eliminates the need for manual third-party power-of-attorney transactions for payment processing.
- 100% Repatriation Guarantee: The single biggest advantage of purchasing property via RDA is the guaranteed repatriation of funds. When you sell your property in the future, the principal amount and full capital gains can be remitted back to your foreign bank account without additional SBP manual approval.
2. Step-by-Step Purchase Process via RDA
| Step | Action Item | Key Requirement / Document |
|---|---|---|
| Step 1 | Open RDA Account | Online setup via partner Pakistani banks (Meezan, HBL, UBL, Alfalah) |
| Step 2 | Select Approved Property | Choose SBP/RDA registered developer or verified secondary market plot |
| Step 3 | Transfer Funds via RDA | Direct digital transfer from RDA account in USD/GBP/AED or PKR |
| Step 4 | Title Transfer & Registration | Biometric verification or digital authorization via bank portal |
| Step 5 | FBR Tax Processing | Automatic withholding tax deduction at official Filer rates |
3. Tax Advantages for NRPs Using RDA
- Active Taxpayer List (ATL) Benefits: NRPs holding valid NICOP or POC cards can register on the FBR portal to obtain Active Filer status. This cuts advance withholding tax on property purchase and sale by 50% compared to Non-Filers.
- Full Transparency for Foreign Remittance: All transactions flowing through RDA leave a clean banking trail, serving as indisputable proof of foreign wealth origin for local and international tax authorities.
4. RDA vs. Traditional Manual Remittance to Local Bank Accounts
- Traditional Manual Bank Transfers: Sending money to regular non-RDA personal bank accounts in Pakistan often leads to tedious regulatory documentation when attempting to repatriate sale proceeds abroad in the future.
- Streamlined RDA Exit Mechanism: RDA digital accounts automatically track property investment funds, allowing seamless exit and fund repatriation back to your country of residence upon property liquidation.
Frequently Asked Questions
Q: Can I buy secondary market properties in DHA Lahore using RDA?
Answer: Yes, RDA allows investments in both primary SBP-partner developer projects and verified secondary market properties via bank transfer channels.
Q: What are the FBR advance tax rates for overseas Pakistani filers?
Answer: Filers pay significantly reduced advance withholding tax (typically 3% on purchase for filers vs up to 10%-15% for non-filers depending on property value and ATL status).
Q: Can rental income from Lahore property be deposited back into my RDA?
Answer: Yes, rental income generated from RDA-purchased property can be deposited into your account and converted/repatriated as permitted under SBP rules.
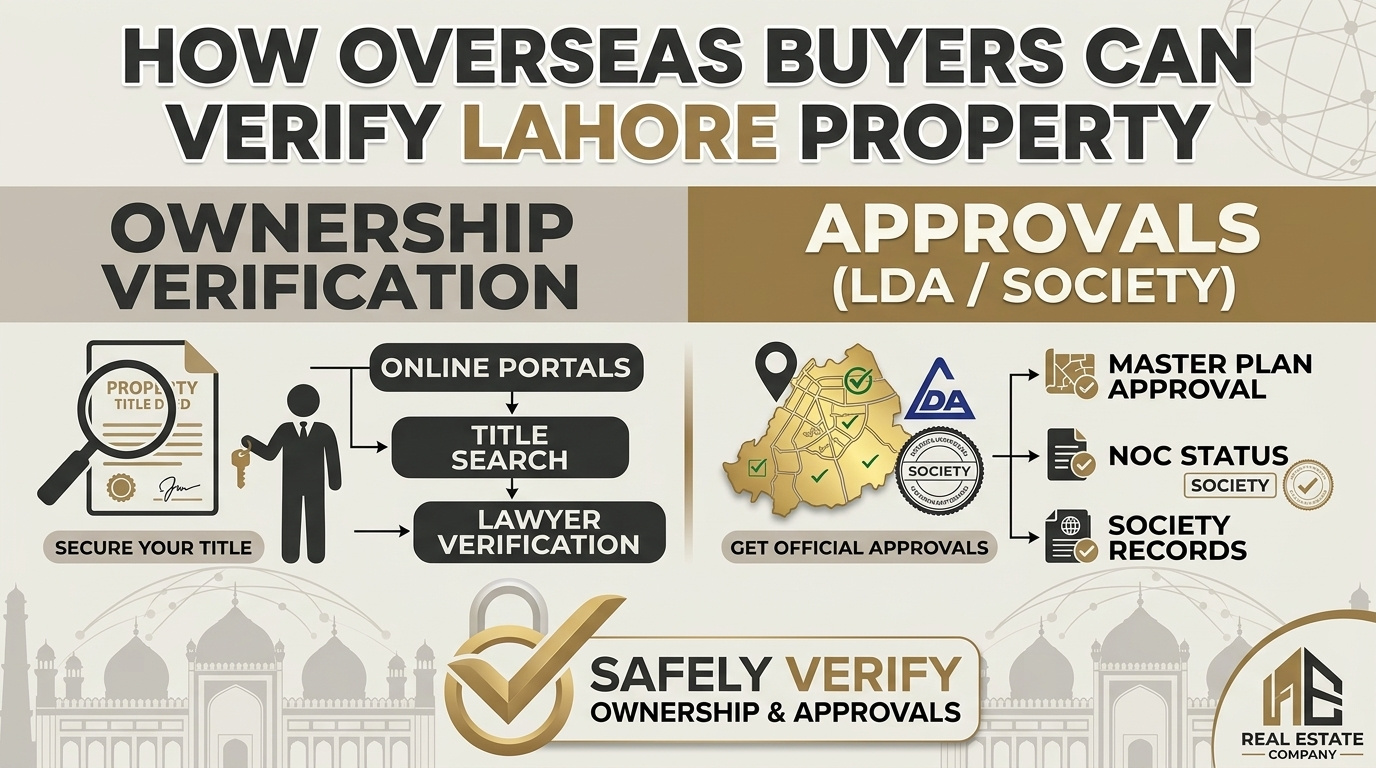
How Overseas Buyers Can Safely Verify Property Ownership and LDA/Society Approvals in Lahore
Executive Introduction
Real estate acquisition in Lahore offers lucrative returns, but remote buyers must conduct thorough legal and regulatory due diligence to protect their capital. Verifying property titles, society NOCs (No Objection Certificates), approved layout plans, and freedom from encumbrances is essential before transferring booking deposits or purchase funds.
1. Verifying Government & Society Approvals (LDA vs. Private Societies)
- LDA Status Verification: For properties located within Lahore Development Authority jurisdiction, check the official LDA illegal housing schemes portal. Verify if the society holds a valid technical approval, cleared NOC, and approved layout plan (LOP).
- Autonomous Society NOCs (DHA, Bahria, Cantonment): Autonomous societies operate under dedicated administrative charters. Always request an official NDC (No Demand Certificate) and perform verification directly at the society's transfer office (e.g., DHA Lahore Main Transfer Branch in Phase 6).
2. Property Verification Checklist for Remote Buyers
| Verification Step | Primary Document / Agency | Risk Mitigated |
|---|---|---|
| Title Deed Verification | Fard-e-Malkiyat / Aks-Shajra from Land Revenue Dept (Patwari/PLRA) | Sellers presenting fake or duplicate ownership documents |
| Society Transfer Letter | Verified Transfer Letter from DHA / Bahria / Private Society | Selling unallocated or duplicate plot files |
| NOC & Approval Check | LDA Portal / RUDA Approval / Cantonment Board NOC | Buying in unapproved/illegal housing developments |
| No Encumbrance Cert. | Bank non-encumbrance letter / Sub-Registrar record | Purchasing mortgaged or court-litigated properties |
| Physical On-Site Audit | Demarcation letter & physical site inspection | Discrepancies between map location and actual plot ground |
3. Digitized Verification Portals in Punjab
- Punjab Land Records Authority (PLRA): Utilize PLRA Arazi Record Centers (ARC) or online land record portals to inspect computerized 'Fard' records for agricultural and rural land integrated into the provincial digital database.
- Online LDA Web Portals: The LDA official web application allows remote users to cross-check approved building plans, approved housing schemes, and list of illegal or non-approved developments in real-time.
4. Step-by-Step Due Diligence Workflow for Overseas Investors
- Step 1 - Document Collection: Obtain clear copies of the seller's CNIC, original title deed/allotment letter, approved building plan, and latest paid utility bills.
- Step 2 - Independent Legal Vetting: Engage an independent real estate lawyer in Lahore to conduct a search at the Sub-Registrar office and inspect official registry books.
- Step 3 - Verification at Society Office: Apply for an official 'Information Verification Slip' or NDC at the housing society transfer branch prior to transferring token money.
Frequently Asked Questions
Q: How do I check if a housing scheme in Lahore is LDA approved?
Answer: You can check approved and unapproved housing schemes directly on the official LDA portal (lda.gop.pk) or by visiting the LDA One-Window Cell.
Q: What is an NDC and why is it mandatory?
Answer: An NDC (No Demand Certificate) confirms that the property has zero outstanding society dues, unpaid taxes, or pending legal disputes.
Q: Can I verify property ownership online in Punjab?
Answer: Yes, computerized land records can be checked online via the Punjab Land Records Authority (PLRA) portal.